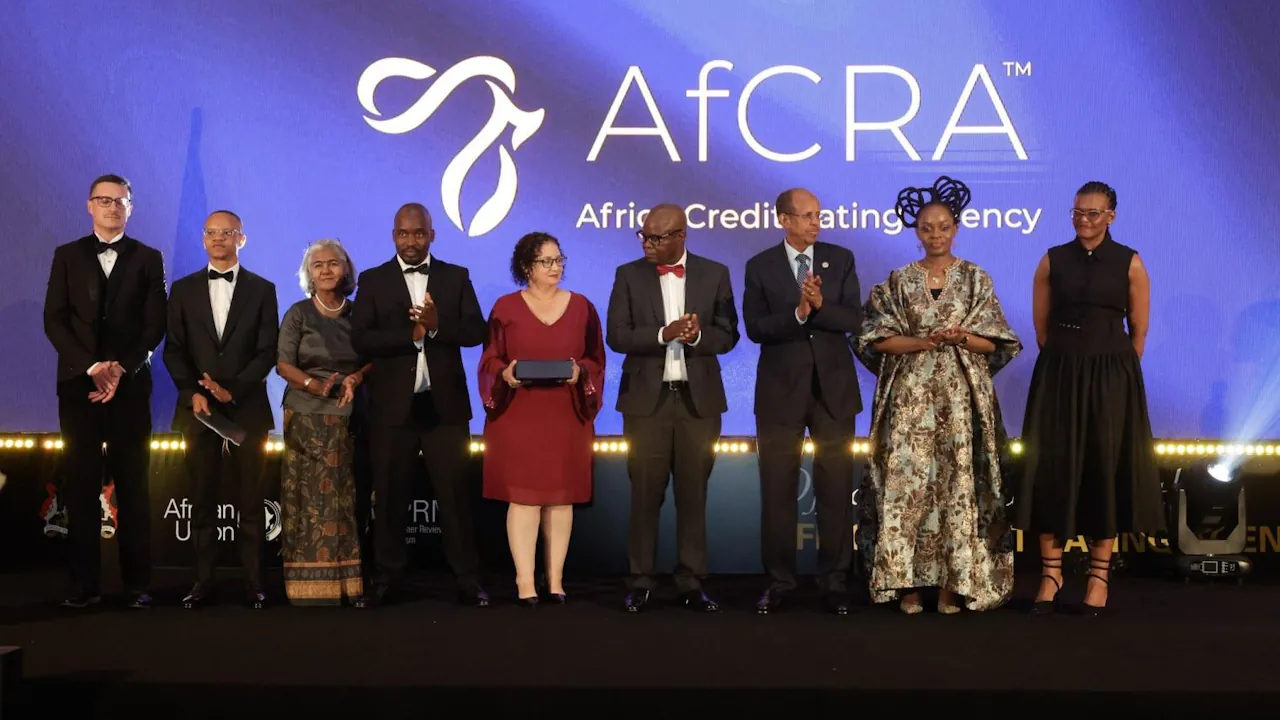

The Africa Credit Rating Agency, launched in Mauritius last Wednesday with the backing of the African Union, is seeking $15mn from investors in return for two-thirds of its equity. Its only shareholder is a South African research firm headed by the man who is also the agency’s interim chief executive.
The terms are in a preliminary investor prospectus, marked confidential but published on AfCRA’s website. It proposes issuing twice as many new shares as now exist, at an indicative $7,500 each, which implies a value of $22.5mn once the money is in. Plus 94 Research, the holder of every existing share, would keep a third.
The prospectus says its figures are not an independent valuation, and calls the pre-investment valuation a negotiated basis, not a guarantee of fair value or future liquidity. It describes a pre-scale revenue profile with no mature earnings history. AfCRA has issued no ratings. Dr Sifiso Falala, the interim chief executive, has said the first should come in the first quarter of next year.
Among the factors the prospectus cites in support of the price is a South African operating company that AfCRA does not yet own. Its Mauritius parent, still in what the document calls its post-incorporation phase, plans to buy a 51 per cent economic interest in Africa Credit Rating Agency (Pty), formerly Sovereign Africa Ratings, which the prospectus describes as licensed by South Africa’s Financial Sector Conduct Authority. The deal is subject to completion, and new investors would hold the stake only indirectly.
Dr Falala, who also runs Sovereign Africa Ratings, has said the purchase should be formalised by the end of the year. The EastAfrican reported that he said AfCRA would acquire the company in full, a larger stake than the 51 per cent economic interest in the prospectus.
The prospectus names no seller and no price for the stake. Its priority areas for the proceeds do not include the purchase, so the document does not say whether any of the money would pay for it. It does not state who will approve buyers of the new shares, or set a minimum investment. Dr Falala has said the choice of approved buyers is still under review.
An undated paper from the African Peer Review Mechanism (APRM), the AU governance body under which the agency was created, and the UN Economic Commission for Africa sketched a different ownership. It envisaged shareholding by African governments and their public institutions, other pan-African rating agencies and multilateral lenders, with seed capital from other pan-African raters. The prospectus excludes government ownership, and Dr Falala has said neither the AU nor the APRM will hold shares.
The paper also called the agency private-sector driven, and ministers endorsed that model in 2023, so the exclusion of governments is consistent with part of the AU’s own design. When the plan settled on a single founding shareholder is not clear. The APRM had named no shareholders, chief executive or board at launch.
The prospectus lists safeguards against shareholder influence, including independent rating committees, separate commercial and analytical staff and recusal rules for conflicts, and says investors would own economic participation, not rating outcomes. It also says the agency’s value depends on the market believing that ratings cannot be directed by shareholders. Daniel Cash, a UK law professor who has advised the APRM on credit ratings, told Semafor that “independence is demonstrated at the point of disagreement”.
Misheck Mutize, the APRM’s lead expert on credit ratings, told The EastAfrican the agency would do away with a 2 per cent “Africa premium” charged by investors if the intervention is “effectively driven”. The UN Development Programme has said only three African sovereigns, Botswana, Mauritius and Morocco, hold an investment-grade rating, though Mr Mutize said Morocco has it from only one agency.
Semafor, which describes Mr Mutize as AfCRA’s chief architect, reported that he acknowledged the agency’s main role would be to steer African savings into African assets, not to change how foreign investors see the continent. The prospectus, however, says a rating alone does not mechanically reduce a borrower’s cost of capital, and that AU provenance does not substitute for analytical performance, regulatory recognition or investor acceptance.
A 2024 Reuters investigation found that most large investors are bound by home-country regulation, or their own rules, on which ratings they may use, which meant they could not rely on an African agency’s scores. The prospectus lists regulatory recognition among its principal risks and says it must be built market by market.
Mr Mutize rejected the suggestion that investors’ trust in the big three limits the agency, saying global investors’ role in its rating discourse is “overpronounced” because they are “centralised around eurobonds”. He put at $4tn the African capital, linked to institutions such as central banks, pension funds, asset managers and sovereign wealth funds, that the agency could influence.
AfCRA will need a licence from Mauritius’s financial regulator, an APRM note cited by Semafor said, and the prospectus does not say whether it has been granted. AfCRA’s website lists Dr Falala as chief executive, without the “interim” used at the launch.